
Episode summary
WMT Earnings Add Consumer Muscle, Rising Inflation Raises Risks
Summary
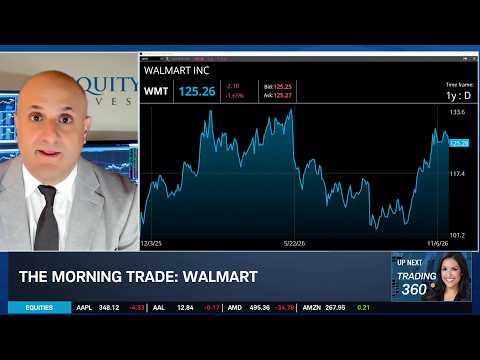
Walmart’s earnings beat and raised outlook did not stop the stock from trading lower on the day, with the host noting pressure from a broader rotation into technology and away from defensive names. The report still showed solid consumer demand: revenue came in at $188.8 billion, comp sales rose 2.9%, global e-commerce sales increased 17%, and U.S. e-commerce grew 23%.
The host said Walmart is benefiting from consumers trading down and from its ability to use pricing power, but the guest argued the market is already pricing in a lot of strength. The guest pointed to Walmart’s roughly 40x P/E versus much faster-growing chip names, and suggested that even defensive leaders could get hit if the market corrects. He described the pullback as partly valuation-driven after the stock had rallied more than 20% since early October.
Operationally, the company raised 2026 guidance again, with net sales expected to rise 4.9% to 5.2% and operating income expected to grow 8% to 8.6%. The guest preferred using options to cap upside rather than buying the stock outright, citing elevated volatility and limited near-term upside at current levels.
Key takeaways
- Walmart beat on revenue and earnings, but the stock still fell about 1.3% as investors rotated out of defensives and into tech, according to the host.
- The guest said Walmart’s valuation is stretched at roughly 40x earnings, making the stock less attractive for further upside from here.
- Management raised 2026 guidance again, with net sales now expected to rise 4.9% to 5.2% and operating income 8% to 8.6%.
- E-commerce remained a major growth driver, with global sales up 17% and U.S. e-commerce up 23%, the host said.
- The guest suggested a covered-call style trade to generate premium and limit downside rather than buying Walmart outright.
- Sam’s Club and Walmart+ strength helped support the quarter, including 9.7% same-store sales growth at Sam’s Club, according to the host.
Notable quotes
“We know that a lot of these consumer products companies have been benefiting from that rotation into more sort of defensive pockets of the markets of late”
“They're gaining market share, as you highlighted, having the ability to do that in the current economic backdr that we have with this k-shaped economy”
“I think it's a good opportunity to cap my long stock by s upside call versus owning the stock”
Topics
- wmt earnings
- consumer sentiment
- rising inflation
- margin pressure
- defensive stock rotation
Companies and tickers mentioned
- WMT
- Walmart
Watch the episode
Watch “WMT Earnings Add Consumer Muscle, Rising Inflation Raises Risks” on YouTube
Summary, takeaways and quote selection by Octagon. Quotes are short excerpts; the full conversation is in the episode.
More from Schwab Network
-
 NDX Options Activity Swells as VIX Rises; What Makes WMT "Meaningful" to Index
-
 Anthropic's Steady Rise and Broader IPO Risks as Company Debuts
-
 Tech Leads into Anthropic IPO, Fed Governors Clash Amid Rate Hike Uncertainty
-
 Preparing for Anthropic IPO; PANW Earnings Surge & INTC Rallies on 18A Deal
-
 KG: Focus Turns to SPX & PANW as Anthropic Readies Public Trading Debut
-
 AVGO Manufacturing Push Stands Out as INTC Battles a PC Slump
Schwab Network, this episode and its artwork belong to their owners. Octagon is not affiliated with the show; this page is an independent summary.
