
Episode summary
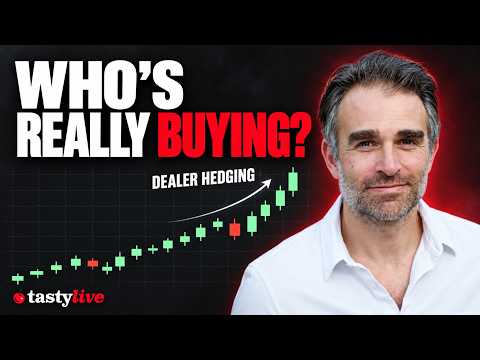
Gamma Exposure Explained by the Guy Who Built the Data
Summary
The host and guest focus on gamma exposure as a way to understand the hedging flow behind stock prices. The guest argues that most options are traded against a small group of market makers, and because dealers hedge to stay delta neutral, their stock buying and selling can sometimes amplify the move already in motion. That is why traders watch open interest, gamma, implied volatility, and the location of put walls and call walls.
The guest says the market is much more short-term than it used to be because zero DTE options now dominate a large share of index flow, making many signals useful only over one to two days. For swing traders, he says longer-dated call buying, changes in term structure, and where positioning is rolling can matter more than intraday noise. He also stresses that the same level can behave differently depending on whether calls are being bought or sold.
The broader point is that options flow is not just directional. The guest says volatility is a second layer of information, and traders need to filter for the setups where the time frame and positioning actually match their trade thesis. He closes by saying Q4 could get more active as realized volatility rises around earnings, the election, and renewed catalyst risk.
Key takeaways
- The guest says roughly 90% of options trade against market makers, so dealer hedging is a key force behind price action.
- He argues gamma matters because it describes how dealers must change stock hedges as the underlying moves.
- He says zero DTE has compressed many options signals into one- to two-day time frames, making longer-dated flow more useful for swing trades.
- He says put walls and call walls matter most when you know whether the flow is mostly buying or selling, not just the strike level itself.
- He expects Q4 volatility to pick up as OPEX clears positions and election-related catalysts approach.
Notable quotes
“90% of all options are traded by a market maker. And that's unique in in single stocks”
“the goal of a put and call wall was to describe where big or the biggest options position shift”
“If you get a very noisy shortdated term structure, right, but that longerdated term structure even 2, three, four weeks out”
Topics
- gamma exposure
- options hedging flows
- market makers
- call walls and put walls
- timeframe risk in options flow
Companies and tickers mentioned
- SpotGamma
Watch the episode
Watch “Gamma Exposure Explained by the Guy Who Built the Data” on YouTube
Summary, takeaways and quote selection by Octagon. Quotes are short excerpts; the full conversation is in the episode.
More from Tastylive
-
 Nvidia Is Down 37% and Traders Can’t Agree What Happens Next
-
 Tim Knight Calls This the Great Sell-the-News Event
-
 Tim Knight Says Earnings Are Done, Data Is Done, and Nothing’s Left to Move It
-
 There's No Single Volatility Number for a Stock
-
 Markets Grind Higher and Crash Lower, and Here's the Proof
-
 NVIDIA SHOCK: Jensen Huang RESIGNS; NVDA -9% | THURSDAY Nov 12 Live Trading
Tastylive, this episode and its artwork belong to their owners. Octagon is not affiliated with the show; this page is an independent summary.
