
Episode summary
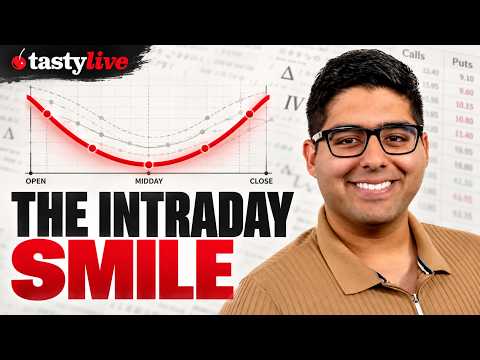
The Intraday Volatility Smile Every Day Trader Should Know
Summary
The episode breaks down 14 years of SPX minute data to show how volatility, range, drift, and price extremes change by hour, with a clear focus on what zero-DTE traders should expect. The host and a guest argue that the session forms an intraday volatility smile: the open is the most active period, midday is the quietest, and volatility picks up again into the close.
The opening 8:30 to 9:30 window produces the largest average absolute one-minute move at 0.033% and the widest high-to-low range at 0.48%. Midday trading contracts, while the strongest average drift shows up around 1:30 to 2:30 p.m. Most hourly windows still show a small positive historical bias, but that advantage weakens as the day progresses.
The most important trading implication is when the day’s extremes get set. The guest says 32.4% of daily highs and 39.6% of daily lows occur in the first hour, while 22% of daily highs occur in the final 30 minutes. They frame that as a warning for traders holding zero-DTE positions too long, especially into the late-day volatility surge.
Key takeaways
- The host says SPX shows an intraday volatility smile, with the open most volatile and midday the quietest.
- The opening hour produces the widest average high-to-low range at 0.48%, well above the rest of the session.
- The guest says 32.4% of daily highs and 39.6% of daily lows occur in the first hour, making early trading decisive for zero-DTE setups.
- The strongest average drift appears from 1:30 to 2:30 p.m., even though most hourly windows are slightly positive.
- The guest warns that the final 30 minutes can redefine highs and lows and make short premium trades more dangerous.
Notable quotes
“SPX activity changes meaningfully throughout the trading day with some hours producing more volatility”
“During that 8:30 to 9:30 period is when the market is the most volatile”
“the opening hour also produces the widest average high to low range, which is at .48%”
“the daily highs and 39.6% of the daily lows occurring during the first, you know, 1 hour”
“by 2:30 p.m., the average remaining return turns negative and the probability of finishing higher falls below 50%”
Topics
- intraday volatility smile
- spx minute data
- zero-dte trading
- daily high low timing
- options volatility
Watch the episode
Watch “The Intraday Volatility Smile Every Day Trader Should Know” on YouTube
Summary, takeaways and quote selection by Octagon. Quotes are short excerpts; the full conversation is in the episode.
More from Tastylive
-
 Nvidia Is Down 37% and Traders Can’t Agree What Happens Next
-
 Tim Knight Calls This the Great Sell-the-News Event
-
 Tim Knight Says Earnings Are Done, Data Is Done, and Nothing’s Left to Move It
-
 There's No Single Volatility Number for a Stock
-
 Markets Grind Higher and Crash Lower, and Here's the Proof
-
 NVIDIA SHOCK: Jensen Huang RESIGNS; NVDA -9% | THURSDAY Nov 12 Live Trading
Tastylive, this episode and its artwork belong to their owners. Octagon is not affiliated with the show; this page is an independent summary.
