
Episode summary
How Trump Accounts Could Make Americans Worse Off
 Wall Street Week
· · 11 min
Summary
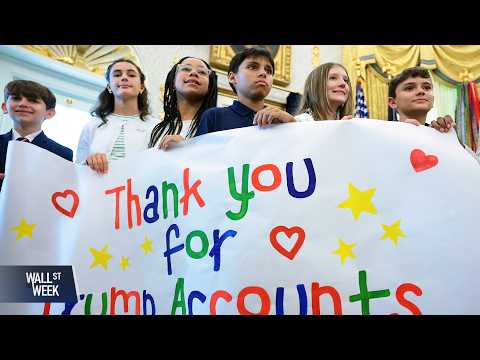
The segment argues that the real test of any new child savings program is not whether it sounds inspirational, but whether it actually leaves families better off after taxes, penalties, and withdrawal rules. It contrasts Trump Accounts with 529 plans and Roth IRAs, noting that 529s and Roths offer tax-free growth and tax-free withdrawals for qualified uses, while Trump Accounts tax earnings as ordinary income when the child can withdraw at 18. That structure, critics say, could make the accounts less useful for families who need flexibility most.
The discussion also compares the federal program with Connecticut’s baby bonds, which are explicitly designed to reduce wealth inequality and give eligible children a larger launch pad. By contrast, an analyst argues Trump Accounts may widen gaps if higher-income families can keep money invested longer while lower-income families are forced to withdraw earlier and absorb taxes or penalties. The episode also emphasizes that auto-enrollment helps, but automatic contributions and clear rules matter just as much if families are going to use these accounts effectively.
The practical lesson is that compounding only works when money stays invested long enough, and many households are still juggling student debt, credit-card debt, and day-to-day costs. For some families, a 529 remains the best tool for education savings; for others, the new accounts may be more confusing than helpful unless the rules are simplified.
Key takeaways
- The host argues Trump Accounts may be more complicated than helpful because earnings are taxed as ordinary income at withdrawal, unlike 529s and Roth IRAs.
- An analyst says lower-income families could be worse off if they pull money out earlier and lose the benefits of long-term compounding.
- Connecticut Treasurer Erick Russell says baby bonds are designed to address wealth inequality directly, unlike the universal federal program.
- The episode says auto-enrollment is important, but automatic contributions and regular investing matter more if families want compounding to work.
- A JPMorgan education-savings specialist says 529 plans remain the best fit for families saving for college or vocational school.
Notable quotes
“the miracle of compounding. As Benjamin Franklin's popular saying goes, "a penny saved is a penny earned." And Einstein added to it that compounding is the most powerful force in the universe”
“Americans are saving less and borrowing more. Now governments are stepping in to jumpstart savings programs starting as soon as children are born”
“-The Trump Account is this account that's put on top of the existing savings ecosystem. But it isn't a simplification”
“529s and Roth IRAs have their advantages come tax season because qualified withdrawals including all investment gains come out completely tax free”
“if these rules aren't changed over the next decade or so, I think these accounts could actually make wealth inequality worse, not better”
How the episode opens
Westin: This is a story about the miracle of compounding. As Benjamin Franklin's popular saying goes, "a penny saved is a penny earned. And Einstein added to it that compounding is the most powerful force in the universe.
But for that force to work there have to be those pennies saved. And, unfortunately, today Americans are saving less and borrowing more. Now governments are stepping in to jumpstart savings programs starting as soon as children are born.
Our colleague Scarlet Fu brings the story from inside America's wallets on the growing options to save more and smarter. -I think I got 3 new puzzles today. -When Wendy Robinson's children were born, she was in her 30s, still paying off her student loans and juggling the many costs of being a young parent.
-For a good chunk of when my kids were little, our costs for child care were more expensive than our costs for our mortgage. -Then came the 2008 financial crisis, a shock that left Robinson and many more Americans deeply in debt. -Our family had the misfortune to buy a house in Arizona in 2006, which turns out to be about the worst time to have ever bought a house.
-When Robinson finally began putting money aside for her son's educational savings fund, she knew she was running out of time. -It was just realizing, "Oh, we've only got like 6 years," because my son was already in middle school by that point. -This summer the Trump administration launched a new savings program that might have helped parents like Robinson, letting families and friends put money into a fund for babies from the day they are born with a 1000 dollar gift from the government to get them started.
It's an idea that National Economic Council director Kevin Hassett has been interested in since the 1990s.
From the episode’s captions: roughly the first two minutes, lightly cleaned. Keep watching on YouTube →
Topics
- student-loan debt
- credit-card debt
- savings accounts complexity
- tax treatment
- retirement and education accounts
Companies and tickers mentioned
- Trump Accounts
Watch the episode
Watch “How Trump Accounts Could Make Americans Worse Off” on YouTube
Summary, takeaways and quote selection by Octagon. Quotes are short excerpts; the full conversation is in the episode.
More from Wall Street Week
-
 What American Manufacturers Are Telling the Fed about the Economy
-
 Europe’s Welfare State Faces a Reckoning
-
 How the Blue Wave Could Reshape America’s Economy
-
 Inside Alaska’s Oil Paradox
-
 Wall Street Week | Blue Wave Economic Impacts, European Welfare Woes
-
 The $40 Trillion Problem Washington Won’t Talk About
Wall Street Week, this episode and its artwork belong to Bloomberg. Octagon is not affiliated with the show; this page is an independent summary.
